

DANA Indonesia Digital Wallet
PT Espay Debit Indonesia Koe
- 4.6
- 3.34K Reviews
- 100.00M
- Downloads
- Free
- Price
Screenshots
DANA Indonesia Digital Wallet Pros and Cons
Pros
- User-friendly interface, easy navigation.
- Fast and secure transactions every time.
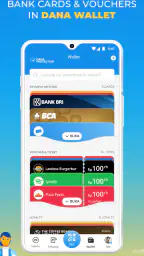
- Supports multiple payment methods.
- Great customer support, responsive team.
- Frequent promotions and cashback offers.
Cons
- Limited international payment options.
- Occasional app crashes reported.
- Requires stable internet connection.
- Some features limited to premium users.
- Verification process can be lengthy.
 Analysis by All-app
When I choose a digital wallet, I care less about a long feature list than about whether it fits the payments I already make. I want a quick way to handle everyday spending, a clear flow for routine transactions, and a reason to open it instead of reaching for cash or a card. DANA is worth considering if you live in Indonesia and want those tasks gathered in one phone app, but it works best as a practical payment tool rather than a replacement for every financial service.
It is a free finance app from PT Espay Debit Indonesia Koe, and its large audience suggests it has become a familiar option for many local users: it has over 100 million installs and a 4.6 average from around 9.1 million ratings. Its age rating is Everyone. Those figures show reach, not a guarantee that every transaction will suit your needs, so I would still judge it by the payments you personally expect to make and the places where you can use it.
Start with the payments you actually make
Before installing another wallet, I’d list the jobs I want it to do. Is the main need paying a household bill, topping up a phone, sending money, or checking out at a shop without carrying cash? DANA is more appealing when several of those needs come up regularly. If you only want a way to pay at one particular store, a bank app, card, or another wallet already accepted there may be simpler.
That distinction matters because a digital wallet is useful only when it fits the local routine around it. An app can feel smooth in its menus and still be inconvenient if the people or merchants you pay do not use it. I’d check whether the services I rely on are available in the app and whether my usual payment points accept its QR option before making it my default. Keeping another payment method available is sensible until I know how reliably it fits my week.
Where DANA fits into everyday life
The first thing that struck me about DANA was its sleek interface. You know how some apps just feel right? This is one of them. Navigating through the app is a breeze, and it’s designed with the user in mind, making every transaction feel like a walk in the park. Whether it's paying bills, transferring money, or shopping online, DANA has got you covered.
Small payments and household routines
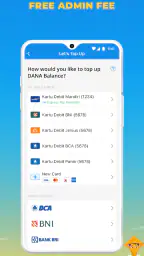
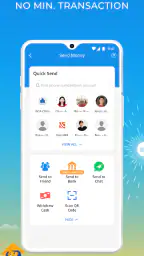
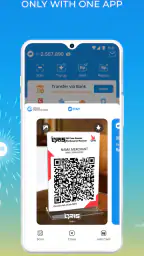
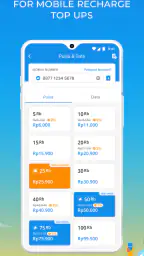
One of the standout features of DANA is its integration with various services. I was pleasantly surprised to find that I could pay for my electricity, water, and even my mobile top-ups all within the app. It saves so much time and effort, it’s like having a personal assistant in your pocket! Plus, the app supports QR code payments, which is a lifesaver when you're out and about without cash.
A realistic use for me would be to handle a phone top-up during a lunch break, then pay a household bill later without switching between separate service apps. At a shop that accepts QR payments, I could also use the wallet rather than searching through my bag for cash. The benefit is not just speed: routine payments can be kept in one place, making it easier to remember which app I used. I would still check the amount and recipient before confirming, especially when paying a bill or sending money, because convenience does not remove the need to verify a transaction.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
A useful habit is to treat the first few payments as a setup period. I’d try a small, familiar transaction before relying on DANA for an urgent bill, then note which steps are required and where I need to check the final amount. That gives me a chance to learn the flow when there is no pressure. It also helps reveal whether the services I personally use appear in a straightforward way, rather than assuming that every provider or merchant will be equally convenient.
Security, rewards, and the trade-offs
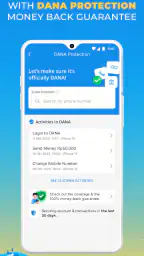
Security is always a top concern for me, and DANA doesn’t disappoint. With its robust security features, including biometric authentication and a secure PIN, I felt confident using it for all my transactions. The peace of mind this brings is invaluable, especially in today’s digital age where security breaches are all too common.
Biometrics and a PIN make access feel more controlled, but they are not a reason to let my guard down. I would avoid sharing a PIN, keep my phone locked, and pause before approving a payment I did not initiate. I also prefer to keep a wallet balance tied to the amount I expect to use rather than treating any payment app as a place to store money indefinitely. That is a personal risk-management choice, not a claim that the app requires a particular balance or offers a specific account arrangement.
Now, let’s talk about promotions. Who doesn’t love a good deal? DANA frequently offers cashback and discounts on transactions, which is a huge bonus. It’s not every day that paying for your favorite coffee or buying essentials can earn you some money back, right? This feature alone makes it worth trying out.
I would treat a promotion as a bonus, not the reason to choose a payment method. Offers can shape where I shop or which payment route I pick, so I’d check the conditions shown for each deal and make sure the underlying purchase is something I wanted anyway. A discount is less useful if it nudges me into spending more or makes a simple payment harder to track. The sensible approach is to compare the final cost and the steps involved, rather than assume every transaction earns a reward.
When another payment option makes more sense
Compared with a bank’s own app, DANA’s appeal is that it brings wallet-style payments and everyday service tasks together. A bank app may be the better choice when I want to manage my banking relationship directly or prefer handling payments from that account. A physical card can be more familiar for someone who wants to tap or pay without opening a wallet app, while cash remains useful where phone access, battery, connectivity, or acceptance is a concern. These are different tools for different situations; I would not choose DANA on the assumption that it replaces them all.
It may also be the wrong fit for someone who rarely makes digital payments, does not want another account or app to manage, or mainly pays merchants that do not accept the methods they use. If I were choosing a wallet for a family member, I’d first consider whether they are comfortable with smartphone payments and whether they have a reliable way to secure the device. A familiar cash or card routine can be better than adding an app that the person will not use confidently.
For a frequent user, one practical trade-off is concentrating several small payment tasks in one place. That can reduce app-hopping, but it also means I need a clear personal routine for checking completed payments and keeping track of spending. I would review transaction records as part of my normal money check, rather than relying on memory or on promotional messages. That small habit is particularly helpful when a wallet is used for snacks, transport-related purchases, top-ups, and bills in the same week.
Getting started without making it your only option
If I were trying DANA for the first time, I would begin with one low-stakes task I already understand, such as a phone top-up, and confirm the details before submitting it. After that, I’d test a QR payment at a merchant I know accepts it. Only once those basic flows feel clear would I make it part of my regular bill routine. This gradual approach answers a practical question many new users have: I do not need to reorganize every payment at once to find out whether the wallet suits me.
I would also keep an alternative ready for situations where a payment cannot be completed. A wallet is not automatically the best backup if the phone is unavailable or a merchant does not accept it, so cash, a card, or a bank payment method can still matter. For the same reason, I would avoid making a time-sensitive payment for the first time at the last minute. Learning the flow beforehand is a simple way to reduce avoidable stress.
The app is free, which makes trying it less of a financial commitment, but I would still consider the attention cost of another payment account: keeping credentials private, checking transactions, and deciding which method to use. DANA is currently on version 2.106.0 and supports Android 5.1 or later, so older compatible phones may be able to run it. I would keep the app updated when possible and use a device I can protect with a screen lock.
Another question worth considering is whether a digital wallet is appropriate for the kind of spending I want to manage. DANA can make individual payments convenient, but convenience alone does not create a budget. If I am trying to reduce impulse purchases, I may prefer a method that makes spending feel more deliberate, or I may set a personal limit on how often I use the wallet. The best payment tool is not always the one that removes the most friction; it is the one that supports the habits I want.
Who is likely to appreciate it
DANA is a strong candidate for someone in Indonesia who regularly handles supported bills or top-ups, shops at places that accept its QR payments, and wants a single wallet for several small transactions. It is also appealing if I enjoy managing everyday payments on my phone and am comfortable checking each transaction as I go. Its scale and high average rating make it an established choice, though personal fit still depends on local acceptance and the tasks I actually need it to handle.
On the other hand, I would skip it as a primary payment method if I prefer cash, do not want to manage another app, or need a payment option that works regardless of phone access. I would also choose a bank app or card when that is already the simplest accepted route for my regular spending. DANA is most convincing as an additional everyday tool, not as a reason to discard every alternative.
Why You Should Give It a Go
Now, let’s talk about promotions. Who doesn’t love a good deal? DANA frequently offers cashback and discounts on transactions, which is a huge bonus. It’s not every day that paying for your favorite coffee or buying essentials can earn you some money back, right? This feature alone makes it worth trying out.
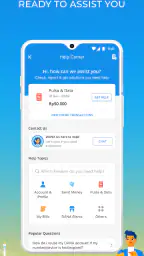
Another aspect that I love about DANA is its customer support. Having quick and responsive customer service can make or break an app. Fortunately, my experience with DANA's support team has been nothing short of excellent. They’re always ready to help, ensuring that any issues are resolved promptly.
In conclusion, if you’re in Indonesia and looking for a reliable digital wallet, DANA is definitely worth checking out. Its convenience, security, and enticing promotions make it a top choice for anyone wanting to streamline their financial transactions. Give it a try and see how it can transform your payment experience. Who knows, it might just become your go-to app too!
My recommendation is to try it for the specific payments you make often, then decide whether it earns a regular place on your phone. The release date was May 7, 2019, and the app has grown into a widely used wallet, but longevity alone is not the deciding factor for me. I’d keep it if its supported services and QR payments genuinely save steps in my routine; if they do not, a bank app, card, or cash may remain the more natural choice. That is the useful distinction: DANA can make familiar transactions easier, but it should fit my habits rather than dictate them.
Frequently Asked Questions
What is DANA Indonesia Digital Wallet?
DANA is a digital wallet application designed to streamline financial transactions in Indonesia. It allows users to make payments, transfer money, and manage their finances directly from their smartphone. With an emphasis on security and convenience, DANA offers features like bill payments, mobile top-ups, and QR code payments, making it a versatile tool for everyday financial needs.
How secure is DANA for financial transactions?
DANA prioritizes user security by implementing robust encryption protocols and multiple layers of authentication. It uses industry-standard security measures to protect user data and transactions. Additionally, DANA offers features such as biometric login and transaction notifications, ensuring that users are aware of any activity on their account, thereby minimizing the risk of unauthorized transactions.
What are the main features of DANA?
DANA offers a wide range of features designed to make financial transactions easy and convenient. Users can perform mobile top-ups, pay bills, transfer money, and make purchases using QR codes. The app also provides a user-friendly interface, transaction history, and budgeting tools to help users manage their finances effectively. DANA's integration with various merchants makes it a comprehensive financial solution.
Is DANA compatible with all smartphones?
DANA is compatible with most Android and iOS devices. Users need to ensure their smartphone meets the minimum system requirements and has a stable internet connection to use the app effectively. Regular updates are provided to enhance compatibility and introduce new features, so keeping the app updated is recommended for the best experience.
Are there any fees associated with using DANA?
DANA offers many of its services free of charge, such as sending money to other DANA users and making payments to partnered merchants. However, there might be fees for certain transactions, such as withdrawals or transfers to non-partnered banks. Users should review the fee structure within the app to understand any potential costs associated with different types of transactions.


